Machinery, vehicles, furniture and computers cost money upfront but wear out over years. Businesses therefore recognise them as balance-sheet assets and allocate lost value across useful lives rather than expensing purchase immediately. Asset depreciation records that loss; fixed asset accounting tracks it. This guide covers Swiss law, straight-line/reducing-balance methods, Federal Tax Administration (FTA) rates and disposals.
What fixed assets include
Assets acquired for long-term use/holding are fixed assets (Art. 960d, para. 1 of the Code of Obligations (OR; CO)); long-term means over twelve months (para. 2). Purchase intention, not price, governs. Tangible/intangible assets appear separately within fixed assets (Art. 959a, para. 1, point 2). Machinery, vehicles, furniture and IT are typical tangible assets.
The law does not prescribe a monetary threshold for capitalisation. Many businesses therefore set an internal threshold to guide their own bookkeeping. Such a threshold is a practical arrangement within the business, rather than a statutory amount. Record the rule you choose and apply it consistently from one financial year to the next. The intended long-term use of the purchase remains the starting point when identifying fixed assets.
Statutory valuation rules
Initial/subsequent valuations cannot exceed acquisition/production cost (Art. 960a, paras. 1–2 CO), subject to special asset rules such as quoted-market-price assets (Art. 960b).
Depreciation reflects use/age; impairment reflects other losses. Both follow generally accepted commercial principles, deducted directly/indirectly from assets against income, never shown as liabilities (Art. 960a, para. 3). Direct means reducing the asset account; indirect retains gross cost with a value-adjustment account.
Additional depreciation/adjustments for replacement and lasting business prosperity are permitted (para. 4). Concrete overvaluation signs require review/adjustment (Art. 960, para. 3). No specific method is prescribed; choose a defensible, consistent one.
“Depreciation and impairment of fixed assets” is a minimum nature-of-expense income-statement item (Art. 959b, para. 2, point 6). Many businesses post disposal gains/losses as extraordinary, non-recurring or prior-period results (point 9). Notes must explain such items unless apparent from the statement (Art. 959c, para. 2, point 12).
Straight-line or reducing balance
Common SME methods:
- Straight-line: equal annual amount: (cost − residual value) ÷ useful years. A CHF 48’000.00 van over five years, no residual: CHF 9’600.00 yearly.
- Reducing balance: fixed percentage of opening carrying amount; annual amounts decline. Suits rapid early losses, e.g. IT.
If set, residual value is the threshold below which depreciation is applied. Many businesses prorate acquisition-year depreciation: practice, not a statutory value. Document your rule; consistent presentation/valuation is a reporting principle (Art. 958c, para. 1, point 6).
FTA standard rates
FTA notice A/1995 “Business enterprises” sets direct-federal-tax rates. Footnote 1 restricts it to Art. 960a, para. 3 CO depreciation. Standard rates apply to carrying amount (section 1); halve them for acquisition-cost depreciation (footnote 3). Selection:
| Asset (notice wording, shortened) | Standard carrying-amount rate |
|---|---|
| Business furniture, workshop/warehouse fittings of furniture character | 25% |
| Production apparatus/machinery | 30% |
| Motor vehicles of all types | 40% |
| Office machines | 40% |
| Data-processing equipment (hardware/software) | 40% |
| Tools, implements, equipment, scaffolding, pallets, etc. | 45% |
| Commercial, office/bank buildings (building alone) | 4% |
- Asset (notice wording, shortened)
- Business furniture, workshop/warehouse fittings of furniture character
- Standard carrying-amount rate
- 25%
- Asset (notice wording, shortened)
- Production apparatus/machinery
- Standard carrying-amount rate
- 30%
- Asset (notice wording, shortened)
- Motor vehicles of all types
- Standard carrying-amount rate
- 40%
- Asset (notice wording, shortened)
- Office machines
- Standard carrying-amount rate
- 40%
- Asset (notice wording, shortened)
- Data-processing equipment (hardware/software)
- Standard carrying-amount rate
- 40%
- Asset (notice wording, shortened)
- Tools, implements, equipment, scaffolding, pallets, etc.
- Standard carrying-amount rate
- 45%
- Asset (notice wording, shortened)
- Commercial, office/bank buildings (building alone)
- Standard carrying-amount rate
- 4%
Land generally receives no depreciation (footnote 4). The higher building-only rate requires remaining building carrying amount/cost capitalised separately. Missed depreciation is recoverable for tax only in section 3’s narrow poor-business-performance cases, with proof. Special cantonal procedures also exist (section 4); cantonal practice may govern cantonal/municipal taxes. These figures reflect the notice listed by the FTA under 10 October 2023. Check original rates and consult your fiduciary before use.
Maintain the asset register
Useful fields:
- asset number/description;
- balance-sheet asset and depreciation expense accounts;
- acquisition date/cost;
- residual, useful life/rate and method;
- carrying amount, accumulated depreciation, disposal date.
Carrying amount equals cost less posted depreciation and must match balance-sheet asset-account balances. Differences reveal postings bypassing the register. At year-end check existence, continued use and value. Inventory or other evidence must support balance-sheet items (Art. 958c, para. 2).
Disposal: sale or retirement
Remove remaining carrying amount and post proceeds to bank. Difference is gain if proceeds exceed carrying amount, otherwise loss. Post depreciation through disposal first. VAT on proceeds is separate and depends on business tax status.
Practical example: Muster Metallbau AG
Fictional Muster Metallbau AG uses calendar years and is not VAT-registered here; all amounts exclude VAT. On Friday, 2 January 2026, it buys:
| No. | Asset | Account | Cost CHF | Method |
|---|---|---|---|---|
| A-01 | Van | 1530 Vehicles | 48’000.00 | Straight-line, 5 years, residual 0 |
| A-02 | Notebooks | 1520 Office machines/IT | 10’000.00 | Reducing balance, 40% |
| A-03 | Workshop fittings | 1510 Furniture/fittings | 12’000.00 | Reducing balance, 25% |
- No.
- A-01
- Asset
- Van
- Account
- 1530 Vehicles
- Cost CHF
- 48’000.00
- Method
- Straight-line, 5 years, residual 0
- No.
- A-02
- Asset
- Notebooks
- Account
- 1520 Office machines/IT
- Cost CHF
- 10’000.00
- Method
- Reducing balance, 40%
- No.
- A-03
- Asset
- Workshop fittings
- Account
- 1510 Furniture/fittings
- Cost CHF
- 12’000.00
- Method
- Reducing balance, 25%
Notice rates: vehicles/data processing 40%, furniture-type fittings 25%. Five-year straight-line van depreciation is 20% of cost, half 40% (footnote 3). Plan, CHF:
| Asset | 2026 depreciation | 2026 closing value | 2027 depreciation | 2027 closing value | 2028 depreciation | 2028 closing value |
|---|---|---|---|---|---|---|
| A-01 | 9’600.00 | 38’400.00 | 9’600.00 | 28’800.00 | 9’600.00 | 19’200.00 |
| A-02 | 4’000.00 | 6’000.00 | 2’400.00 | 3’600.00 | 1’440.00 | 2’160.00 |
| A-03 | 3’000.00 | 9’000.00 | 2’250.00 | 6’750.00 | 1’687.50 | 5’062.50 |
| Total | 16’600.00 | 53’400.00 | 14’250.00 | 39’150.00 | 12’727.50 | 26’422.50 |
- Asset
- A-01
- 2026 depreciation
- 9’600.00
- 2026 closing value
- 38’400.00
- 2027 depreciation
- 9’600.00
- 2027 closing value
- 28’800.00
- 2028 depreciation
- 9’600.00
- 2028 closing value
- 19’200.00
- Asset
- A-02
- 2026 depreciation
- 4’000.00
- 2026 closing value
- 6’000.00
- 2027 depreciation
- 2’400.00
- 2027 closing value
- 3’600.00
- 2028 depreciation
- 1’440.00
- 2028 closing value
- 2’160.00
- Asset
- A-03
- 2026 depreciation
- 3’000.00
- 2026 closing value
- 9’000.00
- 2027 depreciation
- 2’250.00
- 2027 closing value
- 6’750.00
- 2028 depreciation
- 1’687.50
- 2028 closing value
- 5’062.50
- Asset
- Total
- 2026 depreciation
- 16’600.00
- 2026 closing value
- 53’400.00
- 2027 depreciation
- 14’250.00
- 2027 closing value
- 39’150.00
- 2028 depreciation
- 12’727.50
- 2028 closing value
- 26’422.50
Totals are annual subtotals: 9’600 + 4’000 + 3’000 = 16’600 (2026); 9’600 + 2’400 + 2’250 = 14’250 (2027); 9’600 + 1’440 + 1’687.50 = 12’727.50 (2028). End-2026 values: 38’400 + 6’000 + 9’000 = 53’400. 2026 profit falls from CHF 142’300.00 to CHF 125’700.00 (142’300 − 16’600).
31 December 2026 entry: debit depreciation CHF 16’600.00; credit 1530 CHF 9’600.00, 1520 CHF 4’000.00, 1510 CHF 3’000.00.
Tuesday, 2 January 2029: van sold for CHF 21’000.00 versus three-year carrying amount CHF 19’200.00. Debit bank CHF 21’000.00; credit van CHF 19’200.00 and extraordinary income CHF 1’800.00 (21’000 − 19’200). Explain extraordinary gains in notes. VAT registration would add separately posted output VAT on sale; these figures apply only without VAT liability.
Checklist
- Written internal capitalisation threshold
- Each asset registered with number, account, acquisition date/cost
- Method/life/rate defined and retained
- FTA A/1995 tax rates checked
- Annual depreciation posted before locking year
- Register carrying values match balance-sheet accounts
- Disposal dates/proceeds and gains/losses recorded
- Overvaluation signs checked (Art. 960, para. 3 CO)
- Extraordinary items explained in notes
How KMU | base helps
The screenshots show the German interface; KMU | base is also available in French, Italian and English.
Finance | base keeps registers, calculates plans and posts depreciation. Open More › Fixed assets.
1. Record. Add asset captures number, description, asset/expense accounts, cost centre, acquisition date/cost and residual value. The list opens first; open the form as needed. Active accounts 1400–1799 are eligible asset accounts.
2. Method. Select straight-line life or reducing-balance rate; view future plans, cost, posted depreciation and carrying amount. Finance always prorates from acquisition month, counting acquisition month fully, excluding disposal month. January 2026 therefore gives a full year above.
3. Post monthly, quarterly or annual depreciation. Select the period in the closing assistant, review the proposed depreciation and post it through the period end. Finance | base calculates the cumulative amount from the start of the financial year and deducts depreciation already posted. Under Assets › Post depreciation, select the financial year for the annual run, which posts the remaining annual amount. The batch debits the expense account and credits the asset account directly. Post before locking the period or finalising the year; see the Year-end checklist.
Finance | base proposes the amounts from the depreciation plan, so you only check them and do not enter any figures by hand. After each run the register shows cost, posted depreciation and carrying amount, so you can compare the carrying amount with the balance sheet before closing.
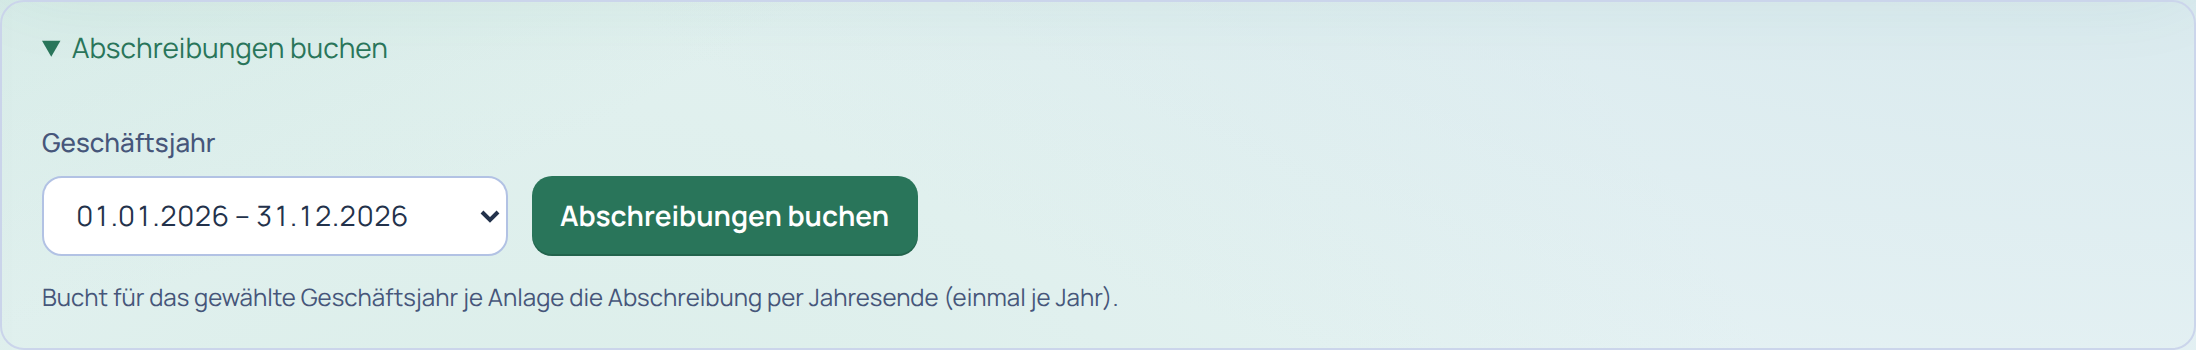
4. Disposal. Enter date/proceeds under Disposal. Finance removes carrying amount, posts bank proceeds and extraordinary gain/loss.
Current-year disposal: Disposal uses the carrying amount from depreciation already posted. Review and post the appropriate partial depreciation in the closing assistant before disposal. The acquisition month counts in full; the disposal month is excluded from prorating. Record VAT on sale proceeds separately in the journal where applicable.
Reconcile the register and journal. The asset register uses direct depreciation: expense account to asset account. Register values reflect acquisition cost less depreciation posted through the depreciation runs. Document additional depreciation under Art. 960a para. 4 CO and other manual journal entries for reconciliation at closing.
Try the Demo or open a test account. See the Finance | base guide and SME chart of accounts. Questions? See the Contact page.
Sources
- Code of Obligations (OR, SR 220), Art. 958c, para. 1, point 6 and para. 2; Art. 959a, para. 1; Art. 959b, para. 2; Art. 959c, para. 2, point 12; Art. 960, para. 3; Art. 960a, paras. 1–4; Art. 960b; Art. 960d, paras. 1–2, as at 1 October 2026: Fedlex (German original), accessed 26.10.2026.
- Federal Tax Administration: Notice A/1995 “Business enterprises” (in German), sections 1–4 and footnotes 1, 3, 4; listed in Direct federal tax notices (in German) under 10 October 2023; accessed 26.10.2026.
This guide does not replace legal or tax advice. Information as at 26 October 2026.